Family Money Management: How to Structure Household Finances Without the Stress
Learn how to manage family money effectively. Compare household account structures, build resilient monthly budgets, prevent financial arguments, and streamline expense tracking effortlessly.
Managing family money is rarely just about numbers on a ledger. It involves balancing individual habits, aligning shared priorities, managing predictable bills, and absorbing unexpected household expenses. Without a structured approach, tracking shared cash flow can quickly lead to misunderstandings, budget overruns, or administrative fatigue.
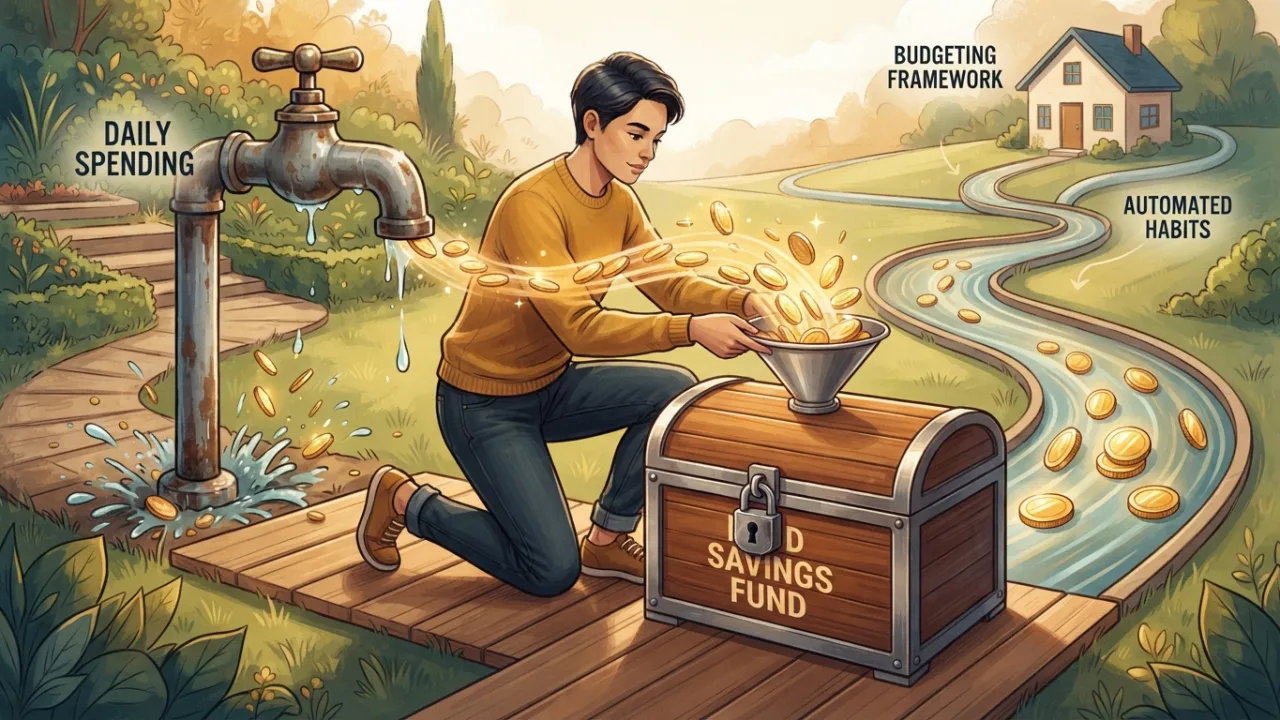
A successful family financial strategy does not require rigid sacrifice or overly complex spreadsheets. Instead, it relies on a clear account structure, open communication, a flexible budgeting framework, and low-friction tracking tools. This guide covers how to organize household finances, establish equitable systems, protect your family against emergencies, and keep daily logging effortless.
Choosing the Right Account Model for Your Household
One of the first decisions in family money management is determining how funds flow between partners or household decision-makers. There is no single correct model; the key is choosing a structure that provides transparency while respecting individual autonomy.
The Joint Account Model
In a fully joint model, all income—regardless of source—is deposited into a single shared account. All fixed obligations, variable day-to-day spending, and long-term savings goals are paid directly from this pool.
- Pros: Maximum transparency, single-point visibility, simplified tracking for unified long-term goals.
- Cons: Potential friction or scrutiny over personal discretionary purchases.
The Hybrid 'Yours, Mine, Ours' Model
The hybrid setup combines shared financial responsibility with personal independence. Partners deposit income into a joint central account to cover shared expenses, housing, debt obligations, and family savings. A predetermined sum or percentage is then transferred to individual personal accounts for unmonitored personal spending.
- Pros: Balances common financial targets with personal spending freedom; significantly reduces petty disagreements over individual hobbies.
- Cons: Requires initial effort to calculate fair contribution percentages and set up recurring transfers.
The Separate Accounts Model
Under this arrangement, partners maintain distinct individual accounts. Household expenses are divided proportionally or split by specific bills (e.g., one partner covers rent or mortgage while the other handles groceries and utilities).
- Pros: Preserves total financial independence and traditional personal habits.
- Cons: Makes it harder to calculate total household net worth, evaluate combined monthly cash flow, or build unified long-term savings strategies.
| Aspect | Joint Account Model | Hybrid 'Yours, Mine, Ours' Model | Separate Accounts Model |
|---|---|---|---|
| Cash Flow Mechanics | All earnings enter one central account. | Income funds shared commitments first; balance splits to personal accounts. | Accounts remain isolated; bills are split manually or assigned. |
| Transparency | Complete shared visibility. | High visibility on bills; complete personal privacy for allowance. | Limited overall visibility into combined household totals. |
| Best For | Couples with unified spending habits and shared goals. | Most modern households balancing joint bills with personal freedom. | Partners entering joint living who prefer financial autonomy. |
Structuring Your Household Cash Flow and Budgeting Framework
Once you choose an account structure, organizing monthly spending requires distinguishing between different types of outgoing funds.
Differentiating Fixed vs. Variable Expenses
Household budgeting breaks down when fixed and variable costs are lumped together. To build an accurate system, categorize your outflows clearly:
- Fixed Expenses: Recurring commitments with predictable amounts, such as mortgage or rent payments, insurance premiums, tuition fees, and debt minimums. These form the base survival line of your household.
- Variable Expenses: Flexible spending categories like grocery shopping, home maintenance, utility bills, dining out, and leisure activities. Because variable expenses fluctuate, they require active monitoring to prevent gradual budget creep.
Applying the Flexible 50/30/20 Rule
The standard 50/30/20 budgeting rule offers a practical baseline for structuring net household income:
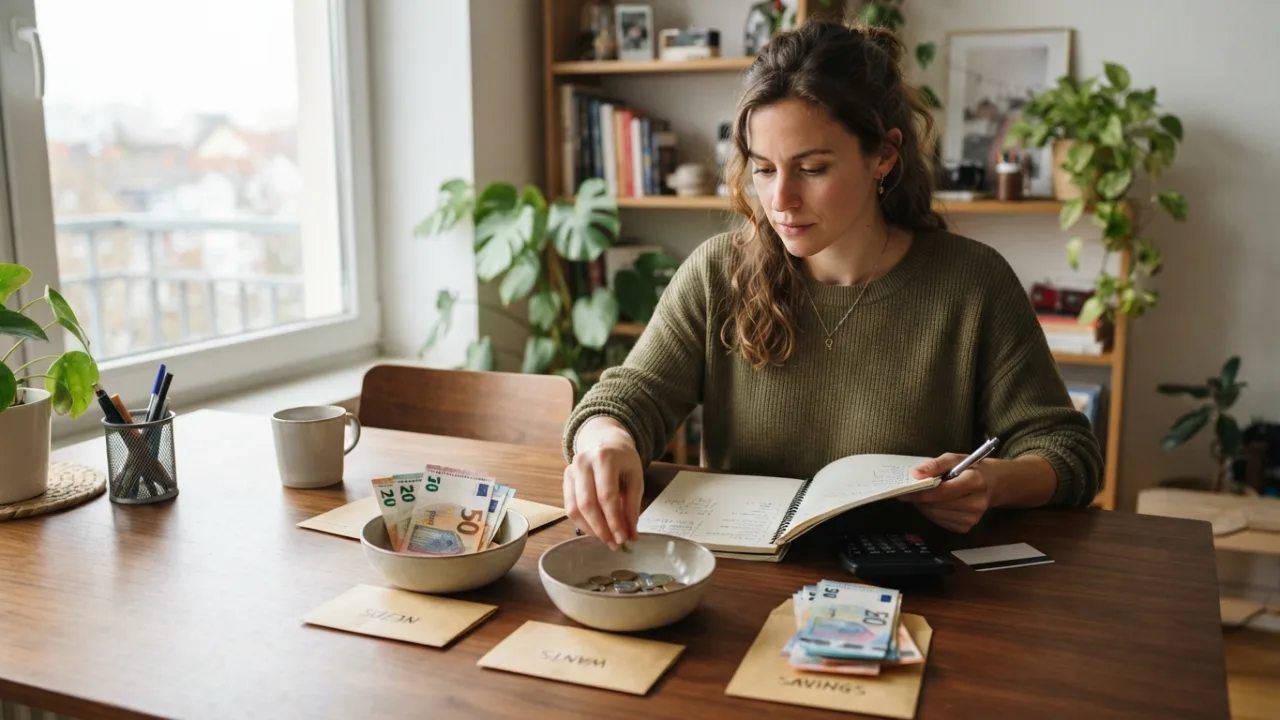
- 50% Needs: Essential living costs, including housing, basic utilities, transportation, minimum debt payments, and basic groceries.
- 30% Wants: Discretionary spending, entertainment, vacations, eating out, and family hobbies.
- 20% Financial Goals: Emergency savings, investment contributions, extra principal payoff, and long-term family reserves.
Treat this breakdown as a guideline rather than a rigid command. In periods of higher living costs or during specific life transitions, your household may allocate 60% to needs and adjust wants accordingly. The goal is maintain consistent savings while keeping variable spending within realistic boundaries.
Fostering Open Financial Communication and Preventing Friction
Tools and formulas only succeed when communication remains open. Misaligned expectations can create tension or lead to financial infidelity—such as hidden debts or undisclosed spending.
Establishing Regular Household Money Check-Ins
Schedule a monthly 15-to-20-minute financial check-in. Use this time constructively to review upcoming large expenses (such as school enrollments, seasonal insurance, or home repairs), evaluate progress toward family savings goals, and adjust category caps for the upcoming month.
Setting Discretionary Spending Thresholds
To eliminate daily friction, agree on a 'no-questions-asked' threshold for unannounced individual spending (e.g., $50 or $100). Any personal purchase exceeding that threshold is discussed beforehand. This preserves trust without micro-managing minor day-to-day decisions.
Building Family Financial Resilience and Future Planning
A resilient family budget protects the household against life's uncertainties while laying the groundwork for the next generation.
Establishing a Household Emergency Buffer
Financial benchmark standards recommend keeping between 3 to 6 months of essential living expenses in an accessible, highly liquid reserve. This buffer should cover critical needs—housing, basic food, utilities, and debt obligations—ensuring your family remains secure during unforeseen income shifts, medical needs, or home emergencies.
Teaching Children Essential Financial Concepts
Involve children early by demonstrating basic financial literacy. Introduce small allowance systems tied to household contributions, help them divide receiving funds into short-term spending and long-term savings, and practice identifying the difference between essential needs and discretionary wants during shopping trips.
Streamlining Expense Tracking with Modern Household Tools
The primary reason family budgets fail is tracking friction. When logging a grocery bill or a quick errand requires sitting down with paper receipts or navigating complex spreadsheets, entry gets delayed, records fall behind, and visibility is lost.
Eliminating Tracking Friction Across Multiple Users
For family money tracking to work long-term, logging transactions must take seconds rather than minutes. Both partners need a shared, accessible platform where cash, card, personal, and joint account transactions can be categorized on the spot.
How MyMoney Simplifies Household Tracking
Designed around the philosophy 'Track your money. Effortlessly.', MyMoney eliminates administrative burdens so families can focus on their goals. Its core capabilities streamline shared money management without adding overhead:
- Unified Accounts & Multi-Category Budgets: Track joint accounts, individual allowances, and specific category caps in one consolidated space. Visual reporting lets both partners view current monthly status at a glance.
- AI Quick Entry & Voice Input: Skip tedious form fills. Type natural sentences or use your device keyboard voice-to-text to state spending naturally—such as 'Spent $45 on groceries at Market'. MyMoney generates a clean draft transaction for user review and instant confirmation.
- AI Receipt Scanner: Simply capture a photo of a paper receipt. The intelligent scanner extracts the merchant, date, and exact spending total into an editable review flow, allowing you to confirm details in seconds.
- Offline-First Sync: Log cash or card spending anywhere—even without an active internet connection. Your entries store locally and sync seamlessly across household devices as soon as you reconnect.
- AI Financial Insights: Gain helpful overview insights into household spending trends. Built strictly as an entry assistant and educational context tool, MyMoney assists your budgeting efforts without offering autonomous financial advice.
By leveraging the proof line—'Type it. Say it. Scan it. Done.'—households establish consistent logging habits that keep financial goals on schedule.
Frequently Asked Questions About Family Money
Should couples combine all their bank accounts?
Not necessarily. While fully joint accounts work well for some, many modern couples successfully use a hybrid model combining a joint pool for shared bills with individual accounts for personal spending autonomy.
How much should a family keep in an emergency fund?
Most financial frameworks advise saving 3 to 6 months of essential household living costs in a liquid savings account to cover unexpected job disruptions, medical care, or urgent home repairs.
What is the easiest way to ensure both partners log daily expenses?
Use an intuitive mobile tracking tool like MyMoney that minimizes entry time. Quick features such as receipt scanning and natural language text entry make logging instantaneous, preventing missed transactions.
Sustaining Long-Term Family Financial Health
Effective family money management is an ongoing system, not a one-time setup. By selecting an equitable account model, differentiating fixed expenses from variable choices, holding concise monthly check-ins, and using low-friction management tools like MyMoney, your family can track cash flow effortlessly, protect against unexpected challenges, and focus on achieving shared dreams together.