7 Everyday Money Habits to Build Financial Confidence (Without Rigid Budgets)
Master your cash flow without rigid spreadsheets or budget burnout. Discover simple everyday money habits that build long-term financial clarity in less than a minute a day.
Managing money effectively rarely comes down to master’s-level accounting or extreme austerity. For most working adults, parents, freelancers, and students, rigid budgets fail not because of a lack of commitment, but because the daily maintenance demands too much time and willpower. When tracking spending feels like a second job, people give up.
Building sustainable everyday money habits offers a practical alternative. By breaking money management down into small, frictionless routines, you can gain clarity over your cash flow, eliminate guilt around everyday purchases, and consistently build savings without spending hours over spreadsheets.
The Power of Micro-Habits in Personal Finance
Behavioral psychology shows that lasting change comes from repeatable micro-actions rather than sudden overhauls. When people attempt to fix their finances overnight by cutting all non-essential spending, they experience decision fatigue and quickly return to baseline habits.
Why Drastic Budgets Fail
Strict budget caps create psychological friction. Restricting every spending category turns minor daily decisions into sources of friction. When an unexpected dinner or utility bill breaks a rigid boundary, it often triggers an all-or-nothing mindset leading to total abandoned tracking for the rest of the month.
Habit Stacking for Cash Flow
A more effective approach is habit stacking: attaching a new financial routine to an established daily habit. Instead of creating a standalone chore, you pair money awareness with something you already do every single day.
- Morning Coffee Check-In: Take 30 seconds while your coffee brews to review yesterday’s spending draft or account balance.
- Evening Commute Wind-Down: Log any point-of-sale purchases before leaving work or closing your laptop for the day.
- Payday Transfer: Immediately route a fixed percentage of income to savings the moment your paycheck arrives.
Shift from Month-End Accounting to Point-of-Sale Awareness
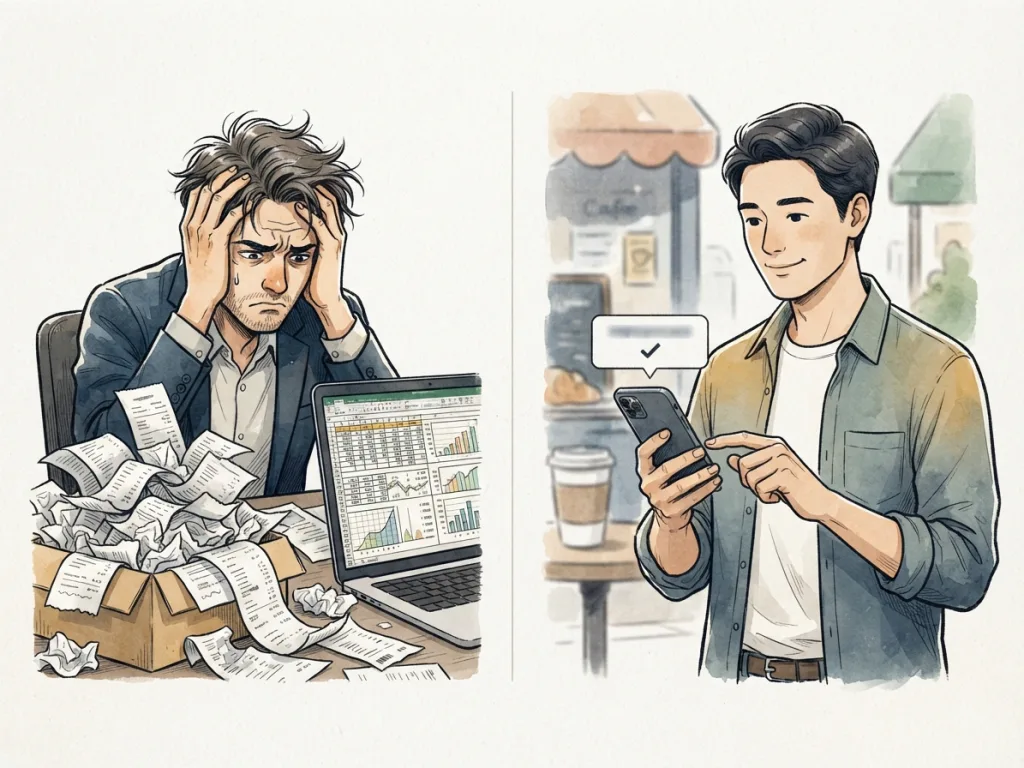
Waiting until the end of the month to organize crumpled receipts or parse through bank statements turns financial management into an overwhelming backlog. By then, the context of why you spent the money is lost, and the insights arrive too late to alter behavior.
The High Cost of Administrative Debt
When you accumulate weeks of untracked expenses, you incur administrative debt. Facing fifty unclassified transactions creates anxiety and memory fatigue. As a result, small cash purchases and minor coffee runs slip through the cracks, leading to unexplainable gaps between bank accounts and budgets.
The 60-Second Daily Check-In
Logging expenses near the point of sale keeps your records accurate and lowers mental fatigue. Capturing a transaction takes mere seconds when done immediately. Spending under a minute a day keeps your financial picture crystal clear while completely eliminating end-of-month stress.
| Approach | Time Commitment | Accuracy | Mental Effort |
|---|---|---|---|
| Month-End Spreadsheets | 2–3 hours monthly | Low (missing details & receipts) | High (dread & fatigue) |
| Point-of-Sale Micro-Tracking | 30–60 seconds daily | High (real-time recording) | Very Low (instant habit) |
Automate Your Discipline with Pay Yourself First
Relying on willpower to save money at the end of the month rarely works. After accounting for daily expenses, dining out, and impulse purchases, the remaining surplus is often zero.
Removing Willpower from Savings
The Pay Yourself First strategy flips this order. On the day you receive income, an automated rule or immediate manual transfer moves a set portion directly into a dedicated savings or investment account. By taking savings off the table immediately, you establish your true discretionary baseline for the rest of the period without constantly negotiating with yourself.
Managing Irregular Expenses with Sinking Funds
Irregular bills—such as annual insurance premiums, holiday gifts, home maintenance, or vehicle repairs—often break monthly financial plans. Creating dedicated sinking funds solves this issue. By estimating an annual expense and dividing it into twelve monthly contributions, you absorb seasonal cost spikes cleanly without disrupting your daily cash flow.
Mindful Spending Rules That Reduce Impulse Buys
Building strong everyday money habits is not about eliminating joy or forbidding small luxuries; it is about cultivating intentionality.
The 24-Hour Pause
Impulse buys are driven by instant gratification. Implementing a mandatory 24-hour pause for non-essential purchases over a specific amount (such as $50) introduces critical space between urge and action. In many cases, the emotional urge fades, saving you money without feeling deprived.
Separating Essential Needs from Upgraded Wants
Everyday spending often contains hidden lifestyle creep. Differentiating between core needs and upgraded convenience allows you to spend thoughtfully. For example, getting high-quality groceries satisfies a primary need, whereas ordering daily food delivery adds a steep convenience premium. Identifying these differences lets you cut spending that yields little satisfaction while preserving purchases that truly add value to your day.
Removing Friction from Daily Expense Tracking
The success of any daily money habit relies directly on low friction. If entering a transaction requires opening three sub-menus, choosing five mandatory tags, and manually calculating taxes, compliance plummets.
Why High-Friction Logging Leads to Abandonment
Behavioral research confirms that as the physical or digital steps to complete a task increase, the likelihood of sticking with that task drops sharply. Modern financial management relies on simple, flexible interfaces that respect your time.
How Smart Tools Streamline Tracking with User Review
Modern applications like MyMoney are built around the core idea: Track your money. Effortlessly. Operating under the philosophy of Type it. Say it. Scan it. Done., the tool eliminates daily tracking friction while keeping full control in your hands:
- AI Quick Entry: Type a natural phrase like “Lunch with team $34” and let the tool automatically format a transaction draft for quick review and confirmation.
- Hands-Free Voice Input: Use your phone keyboard’s built-in voice-to-text to speak your expense aloud, immediately converting your spoken words into a reviewable entry.
- AI Receipt Scanner: Take a photo of a paper receipt to extract merchant details, dates, and amounts directly into an editable draft flow before saving.
- Offline-First Sync: Log expenses anywhere, even without cellular service or Wi-Fi; entries sync smoothly once reconnected.
- Reports & AI Financial Insights: Gain immediate awareness of category trends and monthly cash flow patterns without building complex equations.
Crucially, assistive technologies should never make blind financial guesses or manage accounts autonomously. In MyMoney, every AI-assisted entry acts as an administrative assistant, preparing a draft that you confirm with a single tap. This review step guarantees accurate records while reinforcing your daily mindfulness.
Frequently Asked Questions About Everyday Money Habits
How can I stay consistent with tracking daily expenses?
Pair expense entry with existing habits, such as your morning coffee or evening commute. Using lightweight tools that allow quick natural language entry or receipt scanning reduces logging time to seconds.
What should I do if I forget to track purchases for several days?
Do not attempt to recreate every tiny detail perfectly. Log major missing transactions from your bank app, accept minor discrepancies, and resume your daily micro-habit immediately without feeling guilty.
Is automated saving better than manual saving?
Automated transfers remove the emotional decision-making from saving, ensuring you pay yourself first every payday without relying on leftover cash at month-end.
Conclusion: Building a Financial Routine That Lasts
Mastering your finances does not require painful sacrifices or complex administrative spreadsheets. By adopting simple everyday money habits—such as point-of-sale logging, paying yourself first, using sinking funds for irregular bills, and reducing tracking friction—you build long-term financial security effortlessly.
Focus on consistency over perfection. Embrace tools that simplify data entry, maintain control over every entry, and turn cash flow management into an empowering daily routine. Explore how MyMoney simplifies expense tracking, or visit MyMoney Support to learn more about setting up frictionless daily routines.