How to Track Expenses Effectively for Busy People
A practical guide to tracking personal and household expenses. Learn how to master cash flow, curb impulse spending, and build sustainable savings effortlessly.
Have you ever found your bank account nearly empty by mid-month, even though you feel like you didn't buy anything expensive? This "disappearing money" phenomenon usually stems from lacking a systematic way to track expenses. Small daily purchases—like a morning coffee, food delivery fees, or forgotten digital subscriptions—are often the primary culprits behind financial leaks.
This guide offers a simple, practical, and sustainable method to track your spending so you can master your personal finances without feeling restricted.
Why Does Expense Tracking Often Fail?
Many people begin tracking their income and expenses with high determination, only to give up after a week or two. To fix this, we first need to understand the root causes behind breaking this habit.
Financial Leaks from "Phantom Expenses"
"Phantom expenses" are minor, routine purchases that rarely attract attention. For example: a $3 coffee, a $1 parking fee, or a $5 monthly membership fee. In isolation, they seem harmless. However, when added up over a month, these small expenses can swallow 15–20% of your total income.
Shift Your Mindset: Track to Control, Not to Restrict
Many people mistake expense logging with extreme austerity or deprivation. In reality, the right method to track expenses isn't meant to stop you from enjoying life—it is designed to give you a clear data-driven picture. When you know exactly where your money goes, you gain the power to make proactive, smarter spending choices.
A Sustainable 4-Step Process to Track Expenses
To ensure logging expenses doesn't feel like a chore, follow this minimalist 4-step framework:
Step 1: Log Transactions Immediately
Don't wait until the weekend or month-end to recall your spending. Delaying makes it easy to forget small transactions. The golden rule is to minimize logging friction: as soon as a transaction happens, record it within seconds.
Step 2: Keep Categorization Simple and Practical
Avoid creating too many detailed categories that make sorting complicated. At the beginning, split your expenses into two main groups:
- Fixed Costs: Rent/mortgage, utilities, internet, tuition, loan installments. These remain relatively constant each month.
- Variable Costs: Food, entertainment, shopping, social outings. This category is the easiest to adjust when you want to save money.
Step 3: Set Budget Limits
Based on your net income, establish spending limits for each category. Setting maximum caps in advance helps you detect overspending risks early before it's too late.
Step 4: Review and Adjust Monthly
At the end of every month, spend 15 minutes reviewing your expense summary report. Ask yourself three questions:
- Which expenses exceeded the budget and why?
- Are there phantom expenses that can be cut next month?
- Did my actual savings match my original goal?
Popular Budgeting Frameworks
Once you've built a logging habit, you can apply standard budgeting frameworks to optimize your cash flow.
The 50/30/20 Rule
This classic financial strategy is easy for beginners to implement:
- 50% Needs: Covers fixed costs and essential living expenses (housing, groceries, utilities, transportation).
- 30% Wants: Dedicated to entertainment, dining out, hobbies, and personal shopping.
- 20% Savings & Investments: Debt repayment, building an emergency fund, or long-term wealth accumulation.
The 6 Jars System
This model suits anyone looking for a more granular money allocation strategy:
- Jar 1 – Necessities (NEC – 55%): Everyday living expenses.
- Jar 2 – Financial Freedom (FFA – 10%): Investments generating passive income.
- Jar 3 – Long-Term Savings (LTS – 10%): Major goals like buying a car or home down payment.
- Jar 4 – Education (EDU – 10%): Self-development, courses, and books.
- Jar 5 – Play (PLAY – 10%): Guilt-free spending and personal rewards.
- Jar 6 – Give (GIVE – 5%): Charity, gifts, and helping family or friends.
Comparing Common Expense Tracking Tools
Choosing the right tool determines 80% of your long-term success. Here is a direct comparison of three popular options:
| Criteria | Paper Journal | Excel / Google Sheets | Mobile App |
|---|---|---|---|
| Best For | Beginners, tactile learners who love handwriting | Tech-savvy users who enjoy custom formulas | Busy adults, parents, freelancers, working professionals |
| Pros | Tangible, no digital devices required | Highly customizable, free, handles complex math | Fast entry, automated reports, accessible anywhere |
| Cons | Manual calculations, easy to misplace, no insights | Clunky on mobile phones, time-consuming | Requires picking an optimized app with a friendly UI |
Streamline Expense Tracking with MyMoney
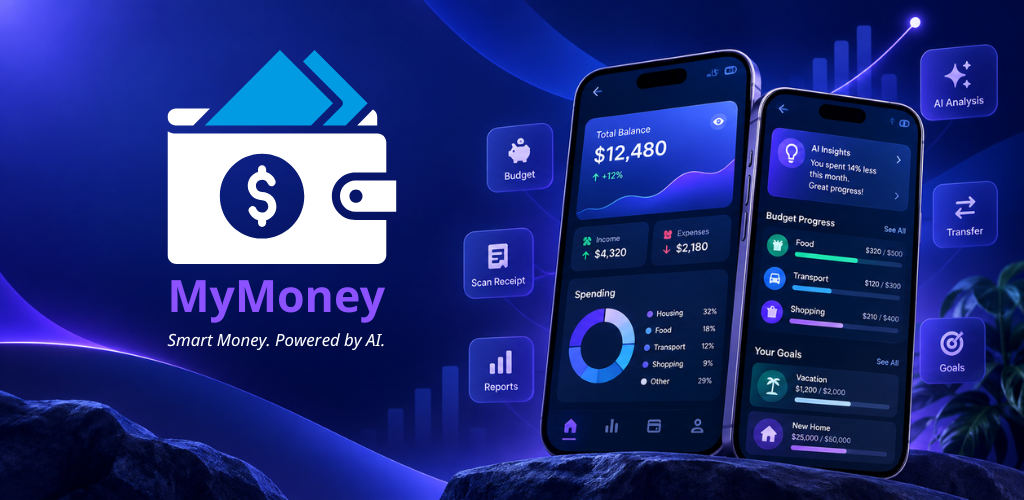
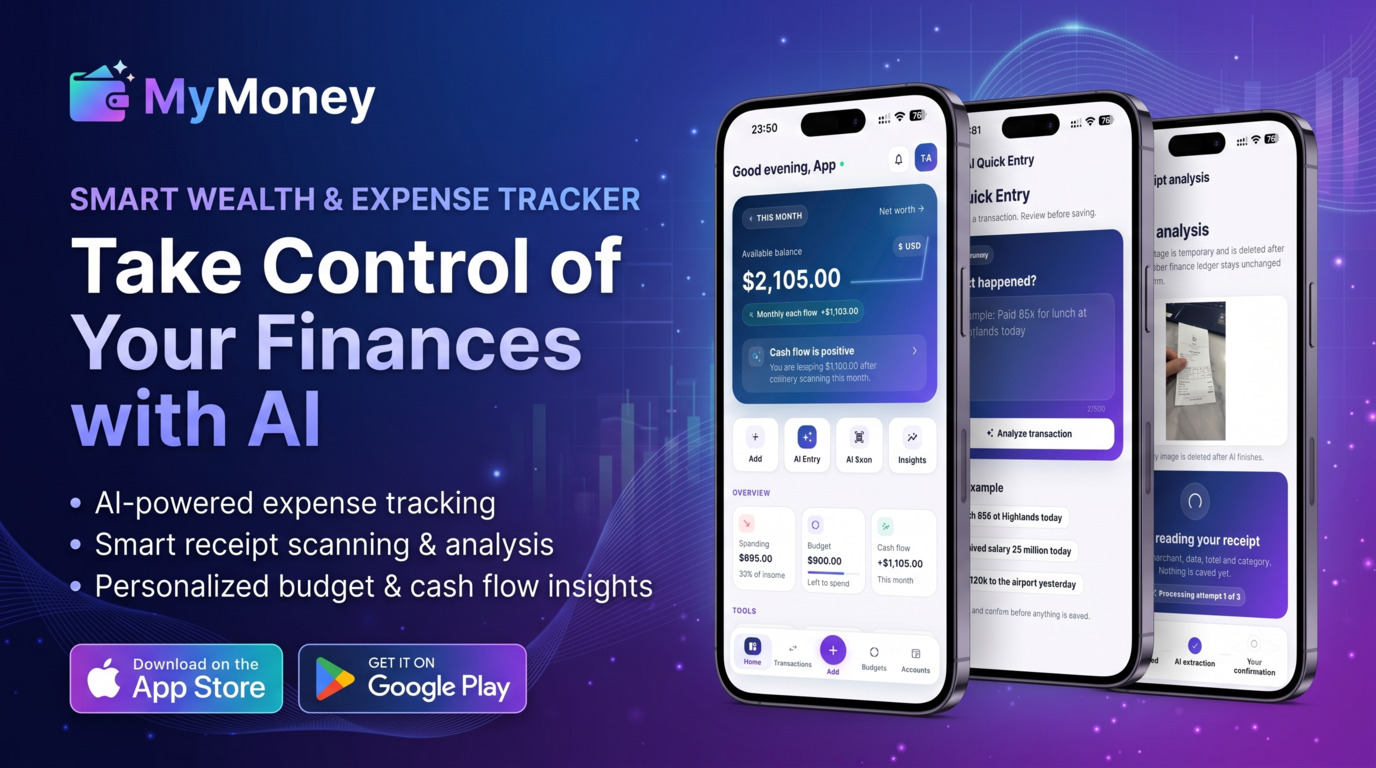
If you want to track expenses quickly without navigating complex steps, the MyMoney app is your ideal assistant, built around a simple vision: Track your money. Effortlessly.
MyMoney makes tracking seamless: Type it. Say it. Scan it. Done. Here is how MyMoney eliminates the friction from financial logging:
Natural Language Logging (AI Quick Entry)
Instead of clicking through multiple menus to select a category, account, and amount, AI Quick Entry lets you type a simple phrase like: Spent $5 on breakfast with cash. The AI parses your input, extracts the amount and category ("Food & Dining"), and prepares a transaction draft. You simply review and confirm it in seconds.
Hands-Free Voice Entry
When you're driving or holding groceries, use your device keyboard's voice-to-text feature to speak your expense. The dictation is captured as text and processed through Quick Entry to build a convenient draft transaction for your review.
Automatic Receipt Scanning with AI Receipt Scanner
When you leave a grocery store or restaurant with a long receipt, you don't need to enter every item manually. Open MyMoney's AI Receipt Scanner and take a photo. The app extracts key receipt information—such as store name, total amount, and date—into an editable review flow so you can confirm before saving.
Visual Reports and Offline-First Architecture
MyMoney supports multi-account management, smart budgeting, and visual chart reports to help you spot spending trends quickly. Best of all, MyMoney features an offline-first design, allowing you to log expenses smoothly without an internet connection and automatically sync data when you are back online.
Note: AI capabilities in MyMoney serve as intelligent logging assistance and data organization tools. Users always retain full control to review drafts and make final financial decisions.
Experience a modern approach to managing your finances by downloading the MyMoney app here.
Common Mistakes to Avoid When Tracking Expenses
- Batching entries at the end of the week: Postponing logs increases forgotten small transactions, leading to inaccurate reports.
- Creating too many subcategories: Over-segmenting categories adds mental friction and causes burnout.
- Viewing tracking as a punishment: Treat spending data as a measurement tool that empowers you to allocate money toward what truly matters.
Frequently Asked Questions (FAQ)
What percentage of my income should I save?
Under the standard 50/30/20 rule, aim for 20% of your income. However, if you are just starting out, set a realistic target of 5–10% and increase it gradually as you gain control over variable costs.
How can I maintain a consistent expense tracking habit?
Anchor logging to an existing daily routine—such as recording right after making a payment or doing a quick check before bed. Additionally, take advantage of quick-entry tools like voice dictation or receipt scanning to eliminate manual effort.
Conclusion
Learning how to track expenses doesn't mean living restrictively or abandoning life's pleasures. It is the essential first step toward mastering your cash flow, removing financial uncertainty, and building a strong foundation for future goals. Start small today: pick a suitable budgeting framework and record your very next transaction.