How to Build a Daily Expense Tracking Habit That Actually Sticks
Stop abandoning your budget after three weeks. Discover how friction reduction, habit anchoring, and forgiving recovery routines make daily expense tracking simple and sustainable.
If you have repeatedly started tracking your spending on the first of the month only to give up two weeks later, you are not alone. Most people who abandon daily expense tracking do not fail because they lack financial willpower or discipline. They quit because their tracking system creates too much operational friction, demands constant micro-decisions, and punishes brief slip-ups with overwhelming administration.
Building a sustainable daily expense tracking habit requires shifting away from high-effort spreadsheets and rigid perfectionism. By reducing entry friction, anchoring spending logs to established daily routines, and using a forgiving recovery strategy when life gets busy, you can keep clear track of your money without turning your daily finances into a stressful second job.
The Real Reason Most Expense Tracking Habits Fail by Week Three
When starting a new personal finance routine, the initial impulse is often to track every detail perfectly. However, behavioral psychology demonstrates that excessive complexity early on quickly leads to habit drop-off.
Over-Categorization and Decision Fatigue
Setting up 30 different spending buckets—such as distinguishing between "Coffee Shops," "Work Lunch," "Takeout," and "Grocery Snacks"—forces your brain to solve a minor taxonomy puzzle every time you spend money. At the end of a long workday, deciding which hyper-specific category fits a multi-item purchase creates cognitive friction. Over time, this repeated decision fatigue causes people to delay entry, leading to backlog accumulation.
The Reconstruction Trap and Memory Decay
When logging is postponed to late evening or the end of the week, human memory decays rapidly. Small digital payments, contactless card taps, and cash tips fade from short-term memory within hours. Trying to reconstruct five days of transactions from bank notifications and paper receipts feels like an unwelcome audit. Faced with a backfilled mountain of admin, most budgeters experience total goal disengagement and abandon tracking altogether.
The 10-Second Rule: Reducing Entry Friction at the Point of Sale
To establish a lasting daily expense tracking habit, the time spent recording a transaction should remain under 10 seconds. The goal at the moment of payment is rapid data capture, not deep statistical analysis.
Capture Transactions Immediately
Logging spending immediately after tapping your card or completing a mobile transfer leverages behavioral momentum. Because the transaction details—amount, merchant, and context—are fresh in your mind, capturing them takes only seconds. Immediate recording relies on the Hawthorne Effect: the simple act of observing and logging your financial actions naturally increases monetary awareness before you even attempt to trim your budget.
Simplify to Broad Categories
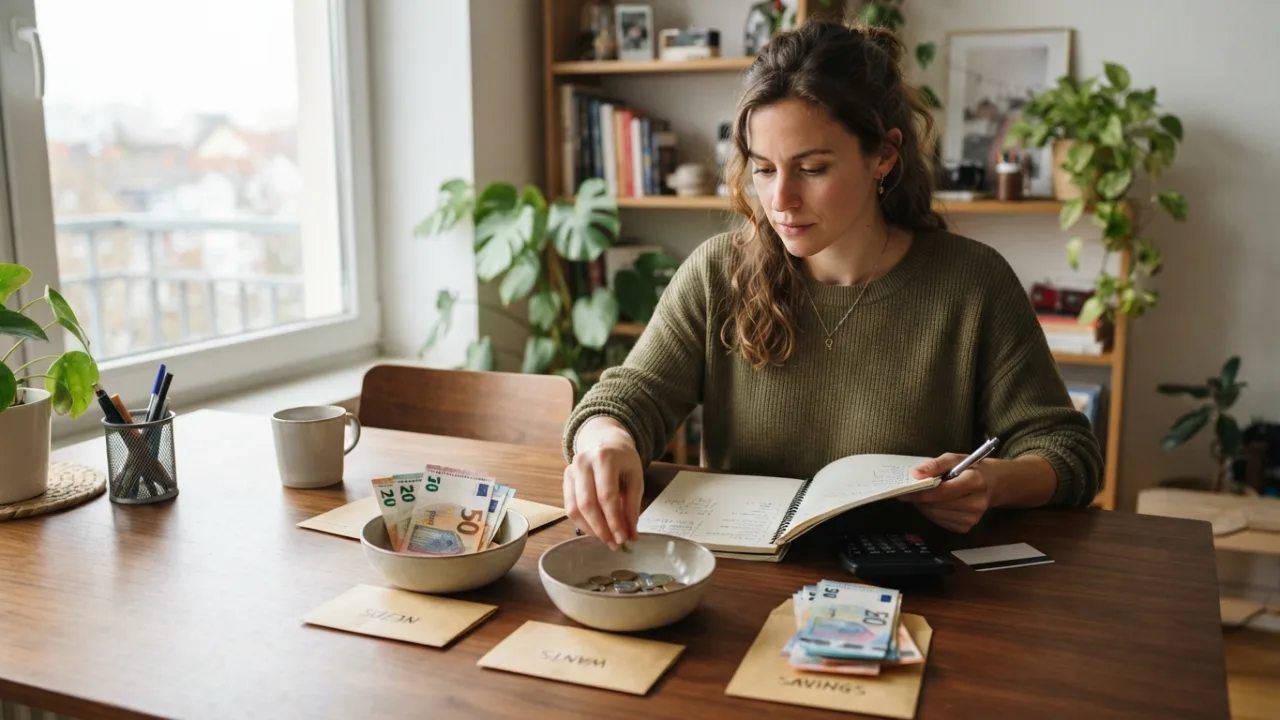
Replace detailed micro-categories with three to five high-level categories during your daily logging. For example, group your initial entries into straightforward buckets:
- Needs: Housing, groceries, utilities, basic transit.
- Wants: Dining out, entertainment, hobbies, casual shopping.
- Savings & Investments: Debt paydown, emergency funds, transfers.
- Unplanned / Other: Urgent repairs or uncategorized expenses.
If you need to analyze dining out versus grocery spending later, you can refine entries during a scheduled review. In the moment, speed and habit continuity matter far more than granular detail.
Habit Stacking: Anchoring Expense Entry to Existing Routines
Relying on sheer memory to open an app or journal rarely works. Behavioral scientist BJ Fogg and author James Clear advocate for habit stacking: connecting a new target behavior to an existing, non-negotiable anchor in your daily environment.
Connecting Micro-Entry to Daily Actions
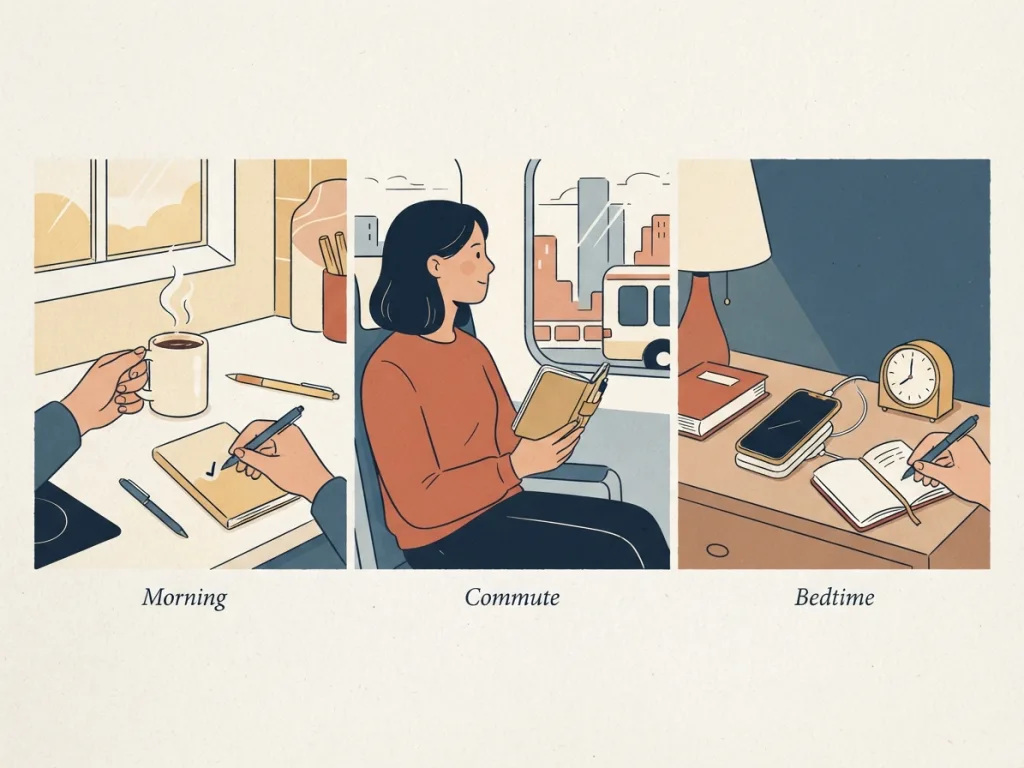
A habit anchor should be a concrete action you perform every single day without fail. The standard formula is: "After I [Current Routine Action], I will [Log My Spending]."
Practical Anchoring Formulas
- The Morning Coffee Anchor: "After I press start on the coffee maker, I will check yesterday’s pending digital transactions and confirm any missing entries."
- The Point-of-Sale Anchor: "After I take my receipt or approve a digital payment on my phone, I will log the purchase total before walking away from the counter."
- The Evening Transit Anchor: "After I sit down for my commute home, I will spend 30 seconds confirming my daytime spending."
- The Bedtime Anchor: "After I plug my phone in for the night, I will open my app to ensure my daily entries balance."
The Forgiving Recovery Protocol: Handling Missed Days Without Quitting
Strict perfectionism is the primary enemy of habit retention. Behavioral psychologists refer to the cycle of minor slip-ups leading to complete abandonment as the "what-the-hell effect." When people miss three days of logging, they often feel they have ruined their streak, leading them to give up for the rest of the month.
Overcoming the "What-the-Hell" Effect
If you miss several days of tracking, do not spend hours digging through old emails and crumpled receipts to reconstruct every missed penny. The admin fatigue caused by backfilling will only reinforce negative feelings toward your finances. Instead, employ a clean slate approach: log a single estimated lump-sum adjustment (e.g., "Un-tracked spending gap: $120") to align your balance, and immediately resume tracking today’s transactions.
Applying the "Never Miss Twice" Principle
Missing a single day is an honest oversight; missing two consecutive days begins forming a new habit of skipping. When life disrupts your routine, your sole objective the following day is to log one single expense. Keeping the streak alive—even with partial data—preserves the neural pathway and maintains long-term momentum.
Decoupling Daily Logging from Weekly Review
A common operational mistake is attempting to analyze spending trends while attempting to log a individual purchases. Mixing data entry with strategic analysis makes daily capture feel heavy and overwhelming.
Daily Micro-Entry for Mindfulness
Daily micro-entry serves one purpose: real-time capture and conscious awareness. You do not need to evaluate whether a $4 coffee was a wise purchase while standing at the counter. Simply log it in under 10 seconds and carry on with your day.
Weekly Macro-Review for Planning
Reserve active analysis for a structured, 5-minute review once a week. Set a recurring appointment on Sunday afternoon to examine your total category totals, adjust budget targets, and evaluate upcoming expenses. By separating fast execution from periodic strategy, daily capture remains effortless.
Comparing Tracking Approaches: Finding Your Low-Friction Balance
Choosing the right methodology depends on balancing data control against friction levels. The table below outlines how common tracking systems compare across key operational dimensions:
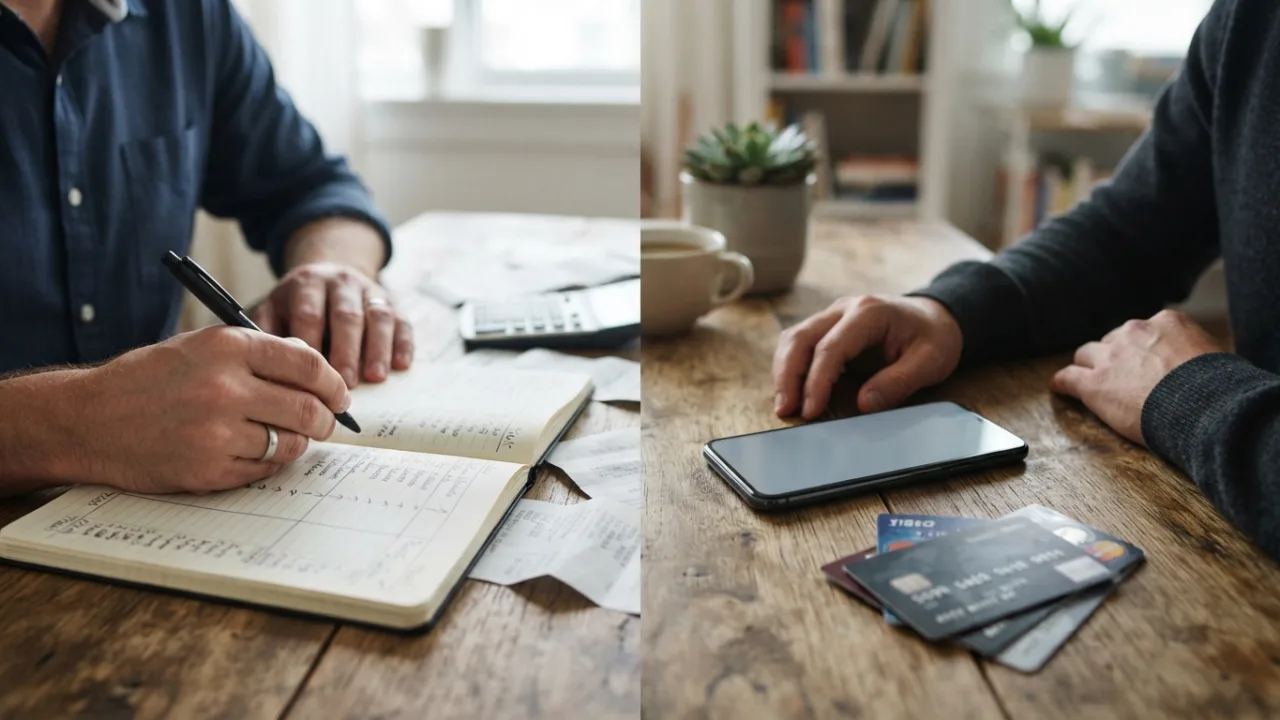
| Dimension | Manual Spreadsheet / Journal | Passive Auto-Sync Apps | Low-Friction Active Entry (e.g., MyMoney) |
|---|---|---|---|
| Friction Level | Very High (manual formatting, requires desktop access) | Zero (completely hands-off background fetch) | Ultra-Low (type, speak, or scan in seconds) |
| Financial Mindfulness | High (but difficult for busy schedules to sustain) | Very Low (easy to ignore background sync entirely) | High (active confirmation encourages intentionality) |
| Risk of Habit Abandonment | High (due to administrative burnout) | Low drop-off, but low behavioral change | Low (fast execution maintains consistency) |
| Data Control & Reliability | High manual control | Subject to broken bank API connections | High (works offline with user-reviewed drafts) |
While passive automatic sync offers convenience, completely hands-off tracking often removes the brief touchpoint that builds real spending intentionality. Low-friction active logging preserves mindful awareness without burdensome administration.
Streamlining Daily Tracking with Assistive Technology
Modern modern tracking tools leverage smart assistance to take the friction out of data entry, leaving you in full control without manual typing burdens.
Natural Language and Voice Drafts
Rather than tapping through multiple dropdown menus to select dates, accounts, and categories, modern assistive flows allow natural input. Using tools like MyMoney, you can simply type "Lunch with team $15" or use your phone's voice-to-text to dictate an entry on the move. The app's AI Quick Entry prepares a transaction draft with the merchant, category, and amount auto-filled, leaving you to perform a simple one-tap review and confirmation.
Receipt Scanning for Multi-Item Purchases
When returning home from a large grocery run or hardware store visit, manual itemization can be intimidating. Leveraging an AI Receipt Scanner allows you to capture complex physical receipts in a single photo. The tool extracts totals, dates, and merchant details into an editable review flow, eliminating manual typing while ensuring your records stay accurate.
Frequently Asked Questions
What should I do if I keep forgetting to log cash transactions?
Cash transactions degrade fastest in memory. Use a point-of-sale trigger: as soon as the cashier hands you your change, speak or type the transaction amount into your tracking tool before putting your wallet away. If you miss it, record an estimated cash total during your evening routine rather than stressing over exact change.
Is 100% accurate data necessary for effective expense tracking?
No. Consistency beats absolute precision every time. Capturing 90% of your expenses reliably over twelve months provides far greater financial insight and behavior change than tracking 100% perfectly for two weeks before quitting.
How many spending categories should a beginner start with?
Start with no more than four or five broad buckets (such as Needs, Wants, Culture/Events, and Savings). Once the daily habit of logging is well established after four to six weeks, you can gradually divide broad categories into sub-categories if you need deeper analytics.
Build a Lifetime Financial Habit
Mastering a daily expense tracking habit is not about enforcing strict self-denial or spending hours inside spreadsheets. It is about building an easy, predictable routine that keeps you connected to your money with minimal effort. By pairing habit anchors with broad categories and modern assistive software, you can turn daily tracking into a simple 10-second check-in that lasts a lifetime.
Ready to build a effortless tracking routine? Explore how MyMoney turns quick text, voice, and receipt inputs into instant transaction drafts so you can track your money, effortlessly.